· 5 min de lectura
Social Security & Medicare Penalties: How to Avoid Them
Millions of Americans pay more than they should because of Social Security and Medicare penalties they never saw coming. Here is what each penalty is, why it happens, and how to protect yourself.
Puntos clave
- Filing for Social Security retirement or spouse benefits before your full retirement age permanently reduces your monthly check.
- Working while collecting Social Security before full retirement age can trigger a benefit reduction of $1 for every $2 earned over the annual limit.
- Missing your Medicare Part B enrollment window results in a 10% penalty for every 12 months you went without coverage — and it lasts forever.
- High earners from two years ago may owe an extra Medicare Part B and Part D surcharge called IRMAA, but it can be appealed with form SSA-44 if your income has since dropped.
- Social Security overpayments must be repaid even if the error was not your fault, but you can request a waiver or set up a payment plan.
- Extra Help (Low-Income Subsidy) is available to help low-income Medicare enrollees pay for Part D prescription drug costs.
¿Quiere saber qué programas se ajustan a su situación? Una verificación gratuita le muestra para qué podría calificar en unos cinco minutos. Sin número de Seguro Social.
Descubrir mis beneficiosEarly Filing Reduces Your Check — Permanently
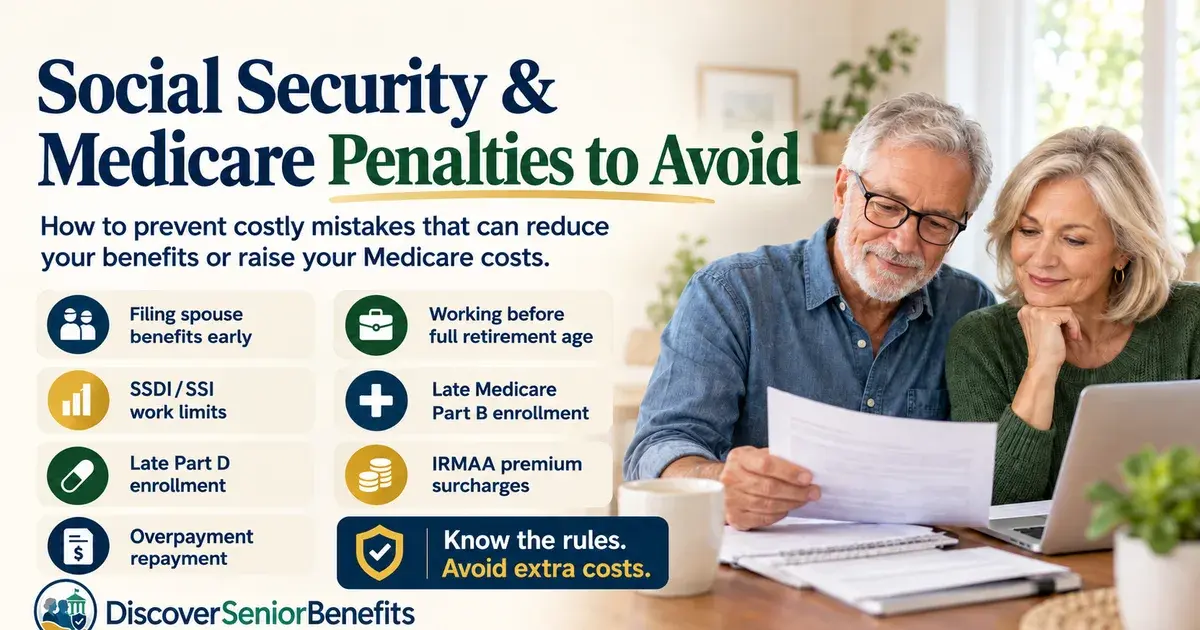
One of the most common and costly mistakes is filing for Social Security retirement benefits before your full retirement age (FRA). Filing at 62 can reduce your benefit by up to 30%.
Spouse benefits work the same way. Even if your spouse is already receiving their full benefit amount, if you claim your spousal benefit early, your portion is still reduced. Both checks take a hit.
A common misconception: many people believe they can file early on their own record and then switch to a full spousal benefit at FRA to erase the reduction. That is not how it works. The reduction on each benefit is locked in based on when you claimed it.
Survivor benefits, divorced spouse benefits, and disabled widow/widower benefits all follow similar rules. Knowing the rules before you file is the single best way to protect your lifetime income.
Working Before Full Retirement Age Can Cut Your Benefits
If you collect Social Security retirement benefits early and continue to work, your benefits can be reduced based on how much you earn.
- Before FRA: If your earnings exceed roughly $24,480 in a year, Social Security withholds $1 for every $2 you earn above that limit.
- The year you reach FRA: The threshold rises significantly (to roughly $65,160), and the withholding rate drops to $1 for every $3 over the limit.
- After FRA: There is no earnings limit at all.
Important: withheld benefits are not lost forever. Social Security credits back the months your benefit was withheld through what is called the Adjustment of the Reduction Factor (ARF). Your monthly check goes up slightly at FRA — but you do not receive a lump-sum check for the withheld amount.
Alimony and passive income such as mineral rights royalties generally do not count as earned income for retirement benefit purposes. SSI (Supplemental Security Income), however, counts nearly all income, earned or not.
For Social Security Disability Insurance (SSDI), the rules are different. SSDI recipients have a nine-month trial work period during which they can earn any amount. After that, earnings must stay below the Substantial Gainful Activity (SGA) limit — currently $1,690 per month — or benefits may stop. VA disability ratings and SSDI are completely separate systems; receiving VA benefits does not automatically qualify someone for SSDI.
Medicare Part B and Part D Late Enrollment Penalties
Missing your Medicare enrollment window is one of the most expensive mistakes a person can make — because the penalties never go away.
Part B penalty: If you do not sign up for Medicare Part B when first eligible (generally at 65, or after 24 months on disability), you face a 10% penalty for every 12-month period you went without coverage. Wait five years and you owe a 50% surcharge on top of the standard monthly premium — for life.
Part D penalty: If you go without creditable prescription drug coverage and do not enroll in a Part D plan when eligible, you owe 1% of the national average Part D premium for every month you delayed — also permanent.
The exception: If you or your spouse has health insurance from current employment at a company with 20 or more employees, you can delay Part B without penalty. Retirement health plans, the Affordable Care Act marketplace, and COBRA do not count as creditable coverage for this purpose. If you believe you were wrongly assessed a Part B penalty because you had qualifying employer coverage, you can challenge it using form SSA-564, filled out by your employer.
If you are already receiving Social Security benefits when you turn 65, Medicare enrollment is automatic — your card arrives about 100 days before your 65th birthday.
IRMAA: The High-Income Medicare Surcharge
IRMAA stands for Income-Related Monthly Adjustment Amount. It is an extra charge added to your Medicare Part B and Part D premiums if your income from two years ago was above certain thresholds.
Most people pay the standard Part B premium. High earners can pay significantly more — in some cases over $600 per month for Part B alone, plus an additional surcharge on Part D.
Social Security looks at your tax return from two years prior to set your IRMAA. This means a large one-time event — a capital gain from selling a home or stock, for example — can trigger a surcharge the following year even if your income has since dropped.
The good news: You can appeal IRMAA using form SSA-44 (Life-Changing Event). If your income has dropped due to retirement, job loss, divorce, or another qualifying event, you may be able to have the surcharge reduced or eliminated. Always confirm the appeal process directly with the Social Security Administration.
Overpayments: What Happens and What You Can Do
Social Security overpayments happen when the agency pays you more than you were entitled to — sometimes through no fault of your own. Regardless of who caused the error, Social Security generally requires repayment.
If repaying the full amount would cause serious financial hardship, you can:
- Request a waiver — if you had no way of knowing about the overpayment and repayment would be unfair.
- Set up a payment plan — repayment can be spread over up to 60 months, interest-free.
The key is to respond promptly when Social Security contacts you. Ignoring an overpayment notice can lead to larger deductions from future checks.
Extra Help: Reducing Medicare Drug Costs for Low-Income Enrollees
Extra Help — also called the Low-Income Subsidy (LIS) — is a federal program that helps people with limited income and resources pay for Medicare Part D prescription drug costs. It can cover premiums, deductibles, and copayments.
The application is straightforward and is handled through the Social Security Administration. When someone applies for disability benefits, Social Security evaluates eligibility for both SSDI and SSI at the same time. Similarly, people who qualify for SSI may automatically qualify for Extra Help.
If you or someone you know is struggling to afford prescription drugs, checking eligibility for Extra Help is one of the most impactful steps to take. Confirm current income and resource limits with the Social Security Administration, as they are updated periodically.
Key Situations That Catch People Off Guard
A few additional scenarios come up often and are worth knowing:
Retroactive benefits past FRA: If you file after your full retirement age, you may be eligible for up to six months of retroactive benefits. However, accepting retroactivity reduces your monthly amount because it lowers the delayed retirement credits you earned.
Collecting SSDI and survivor or spouse benefits: Being on disability does not prevent you from also collecting survivor benefits (as early as age 60) or spouse benefits (as early as age 62). The two benefits offset each other — you receive the higher of the two, not both in full. Your Medicare coverage continues regardless.
Divorce and Social Security: A divorce decree cannot legally bar a former spouse from collecting benefits on an ex-spouse's record. If you were married at least 10 years and are currently unmarried, you may be eligible for divorced spouse benefits. Social Security only looks at the marriage date, divorce date, and the names of the parties — not any other terms in the decree.
Medicare overseas: Original Medicare generally does not cover care received outside the United States. Some Medicare Supplement plans offer limited overseas emergency coverage. Confirm the details of any plan directly with the insurer.
Taxes on Social Security: Whether your benefits are taxable depends on your total income. Only half of your Social Security benefit counts toward the income threshold used to determine taxability. Consult a tax professional for guidance specific to your situation.
Programas en este artículo
- Cómo solicitar Extra Help (Part D Low-Income Subsidy) →
- Cómo solicitar Qualified Medicare Beneficiary (QMB) →
- Cómo solicitar Specified Low-Income Medicare Beneficiary (SLMB) →
- Cómo solicitar Qualifying Individual (QI) →
- Cómo solicitar Supplemental Security Income (SSI) →
- Cómo solicitar State Health Insurance Assistance Program (SHIP) →
Vea para cuáles de estos programas podría calificar. Gratis, sin número de Seguro Social, en unos cinco minutos.
Descubrir mis beneficiosFuentes
Los datos de los programas en este artículo vienen de estas páginas oficiales, las mismas que citan las reglas de elegibilidad.
- Extra Help (Part D Low-Income Subsidy) · ssa.gov · Última verificación · 17 de octubre de 2026
- Qualified Medicare Beneficiary (QMB) · medicare.gov · Última verificación · 17 de octubre de 2026
- Specified Low-Income Medicare Beneficiary (SLMB) · medicare.gov · Última verificación · 17 de octubre de 2026
- Qualifying Individual (QI) · medicare.gov · Última verificación · 17 de octubre de 2026
- Supplemental Security Income (SSI) · ssa.gov · Última verificación · 17 de octubre de 2026
- State Health Insurance Assistance Program (SHIP) · acl.gov · Última verificación · 17 de octubre de 2026
No es asesoría legal ni financiera. La agencia toma la decisión final sobre la elegibilidad.
Artículos relacionados
5 min de lectura
Cambios en Medicare Parte D, consejos de Seguro Social y lo que las personas mayores deben saber ahora
Se acercan cambios importantes en la cobertura de medicamentos de Medicare Parte D y en los planes Medicare Advantage. Esto es lo que las personas mayores y los cuidadores deben entender y hacer antes de la inscripción abierta.
5 min de lectura
Beneficios del Seguro Social que la mayoría de las personas mayores desconoce
Se estima que cada año se pierden $30 mil millones en beneficios sin reclamar. Esta es una guía en lenguaje sencillo sobre los programas del Seguro Social, las opciones de Medicare y los derechos de apelación que las personas mayores y los cuidadores suelen pasar por alto.
5 min de lectura
Fondo Fiduciario del Seguro Social 2034: Qué Significa un Recorte del 19% para Usted
El informe más reciente de los fideicomisarios del Seguro Social adelantó en un año la fecha de agotamiento del fondo fiduciario, hasta 2034. Aquí le explicamos qué significa eso para los beneficiarios actuales y futuros, y qué opciones existen para proteger sus ingresos.
Pregunte sobre este artículo
Obtenga respuestas sobre este artículo con el asistente en cualquier plan pagado.