· 4 min read
Long-Term Care: Options and How to Pay for It
Nearly 7 in 10 people turning 65 will need long-term care at some point. Understanding your payment options — from insurance to Medicaid — can protect your savings and ease the burden on your family.
Key takeaways
- Almost 70% of people turning 65 today will need some type of long-term care in their remaining years.
- The average person uses long-term care services for about 3 years.
- Medicare does NOT cover long-term care — Medicaid may, but only if you meet income and asset limits.
- Hybrid insurance policies can combine life insurance or annuity benefits with long-term care coverage.
- Buying long-term care insurance in your 50s typically means lower premiums and fewer health-related barriers.
- Benefits usually begin when you can no longer perform at least two Activities of Daily Living without help.
Want to know which programs fit your situation? A free check shows what you may qualify for in about five minutes. No SSN.
Find my benefitsWhy Long-Term Care Planning Matters
Someone turning 65 today has almost a 70% chance of needing some type of long-term care during their remaining years. Long-term care means help with everyday tasks like eating, bathing, or dressing — tasks that become harder as health declines.
According to the Department of Health and Human Services, the average person uses long-term care services for 3 years. That's a significant stretch of time, and the costs can be substantial.
Long-term care affects more than just the person receiving it. It places financial, physical, and emotional strain on family members and caregivers too. Having a plan in place can ease that burden for everyone involved.
What Does Long-Term Care Cost?
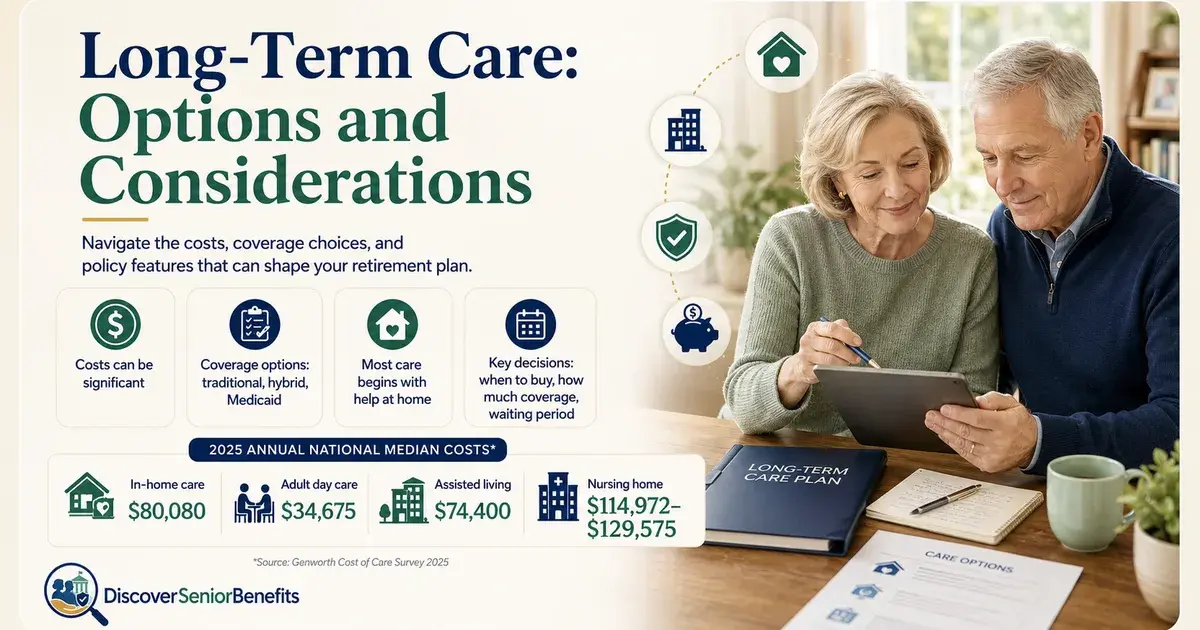
Costs vary depending on the type of care needed. Here are 2025 national median annual figures to give a sense of the range:
- In-home caregiving: about $80,080 per year
- Adult day health care: about $34,675 per year
- Assisted living facility: about $74,400 per year
- Nursing home (semi-private room): about $114,972 per year
- Nursing home (private room): about $129,575 per year
Care often starts with occasional home visits and can grow into full-time nursing care over time. As care needs increase, so do the costs. Knowing these numbers helps when deciding how much coverage to plan for.
Ways to Pay for Long-Term Care
There are several main options for covering long-term care costs. Each has trade-offs.
Government programs Veterans and people with low income may qualify for help through Medicaid or the Veterans Health Administration. Medicaid covers long-term care, but eligibility is based on income and assets — it is generally designed for low-income individuals. Benefits and rules vary by state, and choices about where and how you receive care may be limited.
Important: Medicare does NOT pay for long-term care. It only covers short-term care in limited situations, even for people 65 and older.
Traditional long-term care insurance These policies let you choose the amount of coverage, how long it lasts, and how long you wait before benefits begin. You typically pay an annual premium. However, fewer insurance companies offer these policies today, and premiums can increase after purchase.
Hybrid insurance policies Hybrid policies combine long-term care coverage with either life insurance or an annuity.
- A hybrid life and long-term care policy pays a death benefit to your beneficiaries if you never need care, or lets you draw on that benefit to pay for care if you do. Even if the death benefit runs out, the insurer continues providing long-term care coverage.
- A long-term care annuity builds a pool of money — typically 2 to 3 times your initial investment — that grows tax-free. If used for long-term care, gains are received income tax-free.
Personal savings Paying out-of-pocket gives you flexibility, but it requires a retirement plan strong enough to absorb potentially large, unpredictable costs. Using funds from a 401(k) or IRA may also trigger tax consequences.
When to Buy Long-Term Care Insurance
The best time to buy is generally in your 50s, or when reviewing your retirement plan with a financial advisor. Here's why:
- Lower premiums: Younger buyers typically pay less for the same amount of coverage.
- Better health: The older you get, the greater the chance of a health condition that could disqualify you from coverage.
- Cost of waiting: Premiums for the same level of coverage tend to rise each year you delay.
Waiting until your 70s or 80s may mean paying significantly more — or being denied coverage altogether.
How Benefits Work: Key Policy Features
Understanding how a policy pays out helps you choose the right one.
When benefits begin Most policies start paying when you can no longer perform at least two Activities of Daily Living (ADLs) — such as eating, bathing, or dressing — without help.
Elimination (waiting) period Many policies have a waiting period before benefits kick in. During this time, you pay for care yourself. Some policies reimburse costs from the elimination period once it ends; others do not. Confirm the details before buying.
How much coverage Policies typically pay a set daily or monthly amount (for example, $200 per day or $6,000 per month) up to a total benefit limit. You choose both the amount and how many years the benefit lasts. Buying more coverage than you can comfortably afford is a common mistake — it's better to find a balance that fits your budget.
Inflation protection Since care costs tend to rise over time, adding an inflation protection feature to your policy can help your benefits keep pace.
Premium guarantees Some policies allow the insurer to raise premiums after purchase. Confirm whether your premium amount is guaranteed before signing.
Making the Decision Personal
The right long-term care plan depends on your individual situation.
- Single individuals only need to plan for one person's care, which may mean a smaller policy.
- Couples may want a joint policy that covers both spouses and protects the healthy partner's finances if the other needs extended care.
- Family medical history matters. Hereditary conditions like Alzheimer's disease or diabetes can increase the likelihood of needing long-term care, which may make insurance a stronger consideration.
Long-term care planning is not just a financial decision. Having coverage in place can also reduce the emotional and physical burden on family members who might otherwise step in as caregivers. Always confirm eligibility and policy details directly with the insurer or a qualified advisor, as rules and costs vary.
Programs in this article
- How to apply for Qualified Medicare Beneficiary (QMB) →
- How to apply for Specified Low-Income Medicare Beneficiary (SLMB) →
- How to apply for Qualifying Individual (QI) →
- How to apply for PACE — Program of All-Inclusive Care for the Elderly →
- How to apply for VA Health Care →
- How to apply for VA Aid & Attendance (Improved Pension) →
See which of these programs you may qualify for. Free, no SSN, about five minutes.
Find my benefitsSources
Program facts in this article trace to these official pages, the same ones the eligibility rules cite.
- Qualified Medicare Beneficiary (QMB) · medicare.gov · Last verified · October 3, 2026
- Specified Low-Income Medicare Beneficiary (SLMB) · medicare.gov · Last verified · October 3, 2026
- Qualifying Individual (QI) · medicare.gov · Last verified · October 3, 2026
- PACE — Program of All-Inclusive Care for the Elderly · medicaid.gov · Last verified · October 3, 2026
- VA Health Care · va.gov · Last verified · October 3, 2026
- VA Aid & Attendance (Improved Pension) · va.gov · Last verified · October 3, 2026
Not legal or financial advice. The agency makes the final eligibility decision.
Related articles
5 min read
Medicare, Medicaid & Prescription Drug Benefits Explained
Billions of dollars in senior benefits go unclaimed every year. Here is a plain-language guide to Medicare enrollment rules, prescription drug help, Medicaid savings, and benefit stacking — so you do not leave money on the table.
4 min read
6 Reasons a Medicare Supplement Plan May Not Be Right for You
Medicare Supplement plans offer strong coverage, but they are not the best fit for everyone. Here are six situations where a different path may make more sense for your health and budget.
5 min read
Medicaid Estate Recovery: How It Can Claim Your Home
Medicaid covers long-term nursing home care — but it isn't free. A federal program called Medicaid Estate Recovery can claim your home after you die to repay what the state spent on your care.
Ask this article
Get answers about this article from the assistant on any paid plan.