· 5 min read
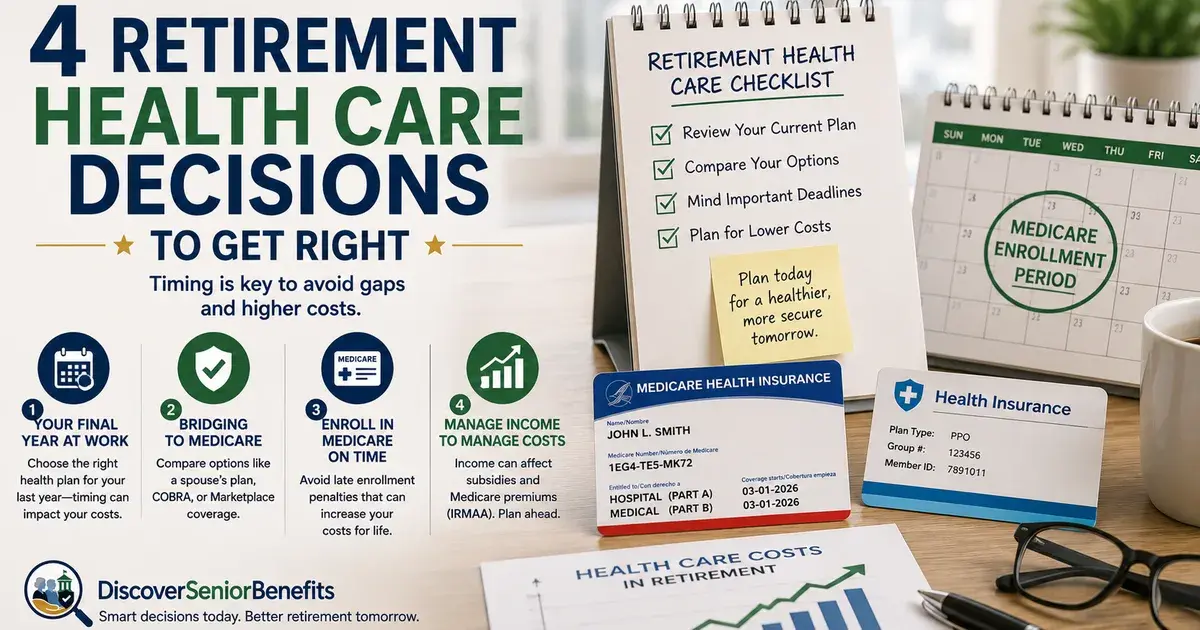
4 Retirement Health Care Decisions to Get Right
Missing a health coverage enrollment window in retirement can mean higher costs that last for years. Here are the four decisions that matter most — and how to approach each one.
Key takeaways
- Missing Medicare or Marketplace enrollment windows can trigger lifetime penalties or coverage gaps.
- The health plan you choose in your final year of work may carry into early retirement, so pick carefully.
- HSA contributions must stop when Medicare begins — contributing after that point can trigger tax penalties.
- If you retire before 65, you can bridge to Medicare through a spouse's plan, COBRA, or Marketplace coverage.
- Higher retirement income can trigger IRMAA surcharges on Medicare premiums, sometimes years after the income was received.
- Medigap insurers in most states only guarantee coverage during the first 6 months you are enrolled in Medicare Part B.
Why Health Coverage Planning Matters So Much
Health coverage decisions around retirement are time sensitive. Miss an enrollment window, and the costs can follow you for years.
One estimate puts average health care and medical spending for a 65-year-old retiring in 2026 at around $185,000 over the course of retirement. That is a large number — but careful planning may help manage some of it.
One factor many people overlook: health insurance costs in retirement are often tied to income, sometimes with a delay. Before Medicare, income affects eligibility for Marketplace subsidies. After Medicare, income can trigger extra charges called Income-Related Monthly Adjustment Amount (IRMAA) surcharges on monthly premiums. How and when income shows up can meaningfully change what you pay across both phases of retirement.
Decision 1 — What Health Plan Makes Sense in Your Final Year of Work?
Your most important health plan choice as an employee happens during your employer's annual enrollment — the year before you retire. The timing of your exit matters.
Retiring early in the year can make a high-deductible health plan (HDHP) less valuable. HDHPs typically pay off only after you meet the deductible. If you leave in March, you may not have enough time to reach it. A plan with copays (like an HMO) could cost less in that scenario.
Retiring later in the year gives you more time to benefit from an HDHP's lower premiums.
Before enrolling, ask yourself:
- Are your current doctors and specialists in network?
- Do you have ongoing treatments or prescriptions to continue?
- How often do you typically seek care?
- Do you prefer lower premiums or more predictable upfront costs?
This plan may carry into early retirement — for example, through COBRA — so it is worth pressure-testing your choice before you lock it in.
Decision 2 — Use or Fund Key Benefits Before You Leave
Two accounts deserve close attention before your last day of work: Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs).
HSAs
HSAs offer a triple tax advantage: pre-tax contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses. Your final working years may be your last chance to contribute — and possibly receive an employer contribution.
Eligibility to contribute ends once you enroll in Medicare, including Part A. Contributing after that point can result in excess contributions, which may be included in taxable income and trigger penalties.
To avoid that:
- If enrolling in Medicare when first eligible (usually the first of the month you turn 65), stop HSA contributions before coverage begins.
- If delaying Medicare enrollment, you may still need to stop contributing up to 6 months before you enroll, because Medicare can apply retroactively in some cases.
Money already in the account remains yours to use even after you enroll in Medicare.
FSAs
FSAs are often "use it or lose it" when you leave employment. The full annual election is available from January 1, even before you have contributed it all through payroll. Qualified expenses must generally be incurred before your last day of work, and claims must be submitted by your plan's deadline.
Health FSAs may be continued through COBRA after you leave, so you do not always need to spend everything before your exit date. Also note: the FSA contribution limit applies per employee, not per household — each working spouse can elect the full amount if both are eligible.
Decision 3 — Bridging the Gap If You Retire Before 65
If you retire before 65, you need coverage to bridge the gap to Medicare. Most employer health coverage ends at the end of the month you retire, so replacement coverage must be lined up in advance.
Spouse or domestic partner's employer plan. If your spouse is working and has employer coverage, joining their plan is often the simplest and most affordable option. Employer plans typically subsidize a large share of premiums. If the employer has 20 or more employees, you can generally stay on that plan and delay Medicare until coverage ends. Note: this delay option does not apply to domestic partners — only spouses.
COBRA. COBRA lets you continue your existing employer coverage for up to 18 months after you retire. You have 60 days to elect it, and coverage can be retroactive. The trade-off is cost — you pay the full premium plus up to a 2% administrative fee. It can be worth it if you want to keep your current doctors or are mid-treatment.
Health Insurance Marketplace. If you lose employer coverage, a Special Enrollment Period allows you to enroll within 60 days. Plans are organized by "metal levels" — Bronze, Silver, Gold, and Platinum — reflecting how costs are split between you and the insurer. Bronze plans have the lowest premiums and highest out-of-pocket costs; Platinum plans are the reverse.
Income matters here. Marketplace subsidies — premium tax credits and cost-sharing reductions — are based on modified adjusted gross income (MAGI). Strategies that can help keep reported income lower include:
- Drawing from taxable accounts with low or no capital gains rather than tax-deferred accounts
- Spreading income over multiple years instead of large one-time withdrawals
- Using Roth withdrawals, which generally do not increase reported income
- Using HSA funds for qualified medical expenses
Always confirm eligibility details with the relevant agency, as rules can change.
Decision 4 — When and How to Enroll in Medicare
Medicare enrollment is one of the most time-sensitive decisions in retirement. Missing windows can mean lifetime penalties, coverage gaps, or higher costs.
Initial Enrollment Period. For most people, this runs from 3 months before the month you turn 65 through 3 months after. Those born on the first of the month have a slightly different window. Missing it can trigger late enrollment penalties.
Delaying Medicare. If you are covered under a spouse's employer plan or continue working past 65 with employer coverage (employer must have 20 or more employees), you can generally delay Medicare. Once that coverage ends, you typically have up to 8 months to enroll in Parts A and B. However, the window to enroll in Medicare Advantage or a Part D prescription drug plan is much shorter — just 2 months after losing active employer coverage.
Traditional Medicare vs. Medicare Advantage.
- Traditional Medicare offers broad access to doctors and hospitals nationwide but does not cap out-of-pocket costs. Many retirees add a Medigap (supplemental) policy to help cover deductibles, copays, and coinsurance.
- Medicare Advantage bundles Parts A, B, and usually Part D into one plan. These plans restrict you to a provider network and may require prior authorization for some services, but often include added benefits like dental, vision, or hearing coverage.
Medigap timing is critical. In most states, Medigap insurers only guarantee coverage during the first 6 months you are enrolled in Medicare Part B. After that, insurers may deny coverage or charge more based on pre-existing conditions. Exceptions include New York, Connecticut, Maine, and Massachusetts.
IRMAA surcharges. Higher income in retirement can trigger IRMAA surcharges on Medicare premiums. For 2026, these surcharges begin at incomes above $109,000 for individuals and $218,000 for couples filing jointly. If your income has dropped due to a life-changing event such as retirement, you may be able to appeal using a specific IRS form — potentially saving up to nearly $975 in 2026.
Free help is available. The State Health Insurance Assistance Program (SHIP) provides free, one-on-one Medicare counseling in every state. Medicare can also be reached directly by phone to find and enroll in plans.
Look Beyond the Monthly Premium
When comparing health coverage options around retirement, monthly premiums tell only part of the story. To get a full picture of costs, also consider:
- Deductibles
- Out-of-pocket maximums
- Copayments and coinsurance
- Prescription drug costs
- Potential eligibility for premium tax credits or cost-sharing reductions
The decisions made in the years just before and after retirement can shape health care costs for a long time. Taking a holistic view — especially during the transition years before Medicare — can help you choose coverage that fits both your health needs and your retirement income plan.
Programs in this article
- How to apply for Extra Help (Part D Low-Income Subsidy) →
- How to apply for Qualified Medicare Beneficiary (QMB) →
- How to apply for Specified Low-Income Medicare Beneficiary (SLMB) →
- How to apply for Qualifying Individual (QI) →
- How to apply for State Health Insurance Assistance Program (SHIP) →
- How to apply for Senior Medicare Patrol (SMP) →
See which of these programs you may qualify for. Free, no SSN, about five minutes.
Find my benefitsSources
Program facts in this article trace to these official pages, the same ones the eligibility rules cite.
- Extra Help (Part D Low-Income Subsidy) · ssa.gov · Last verified · September 21, 2026
- Qualified Medicare Beneficiary (QMB) · medicare.gov · Last verified · September 21, 2026
- Specified Low-Income Medicare Beneficiary (SLMB) · medicare.gov · Last verified · September 21, 2026
- Qualifying Individual (QI) · medicare.gov · Last verified · September 21, 2026
- State Health Insurance Assistance Program (SHIP) · acl.gov · Last verified · September 21, 2026
- Senior Medicare Patrol (SMP) · acl.gov · Last verified · September 21, 2026
Not legal or financial advice. The agency makes the final eligibility decision.
Related articles
5 min read
Medicare Parts A, B, C & D Explained: What Every Senior Should Know
Original Medicare only covers 80% of your medical costs. Understanding your options for covering the other 20% — and knowing the enrollment rules — can save you thousands of dollars and protect your health coverage.
5 min read
4 Retirement Tax Surprises and How to Manage Them
Retirement taxes can be more complicated — and more costly — than many people expect. Here are four common tax surprises retirees face, plus strategies to help reduce the impact.
5 min read
Medicare Part D Changes, Social Security Tips, and What Seniors Need to Know Now
Major shifts in Medicare Part D drug coverage and Medicare Advantage plans are coming. Here is what seniors and caregivers need to understand — and do — before open enrollment.
Ask this article
Get answers about this article from the assistant on any paid plan.