· 5 min read
Step-Up in Cost Basis: What Heirs and Estate Planners Need to Know
When you inherit property, a tax rule called "step-up in basis" can wipe out years of capital gains — saving heirs thousands of dollars. Here's how it works and how to use it wisely in your estate plan.
Key takeaways
- Inherited assets typically receive a new cost basis equal to their fair market value on the date the original owner died, which can eliminate years of taxable capital gains.
- Real estate, stocks, bonds, mutual funds, and collectibles can all qualify for a step-up in basis — but retirement accounts like IRAs and 401(k)s do not.
- Heirs automatically qualify for long-term capital gains tax rates on inherited assets, regardless of how long the original owner held them.
- In community property states, a surviving spouse gets a full step-up in basis on both halves of jointly owned assets — a larger benefit than in common law states.
- Gifting appreciated assets while still living passes along your original cost basis to the recipient, which can result in a larger tax bill when they sell.
- Working with a tax advisor and financial professional can help you decide the best strategy for your specific estate plan.
Want to know which programs fit your situation? A free check shows what you may qualify for in about five minutes. No SSN.
Discover my benefitsWhat Is Step-Up in Basis?
When someone dies and leaves property to a beneficiary, the tax law resets the property's cost basis. The new basis equals the fair market value of the property on the date of the owner's death. This reset is called a step-up in basis (or, in some cases, a step-down if the property lost value).
Cost basis is essentially what was originally paid for an asset. When an asset is sold, taxes are owed on the difference between the cost basis and the sale price — that difference is a capital gain. A step-up in basis erases any gain that built up during the original owner's lifetime, so the heir is not taxed on that growth.
This rule is written into federal tax law (Internal Revenue Code Section 1014). It is designed to prevent double taxation — for example, when an estate has already been subject to estate taxes, heirs should not also owe income taxes on the same gains.
A Simple Example: How Much Can It Save?
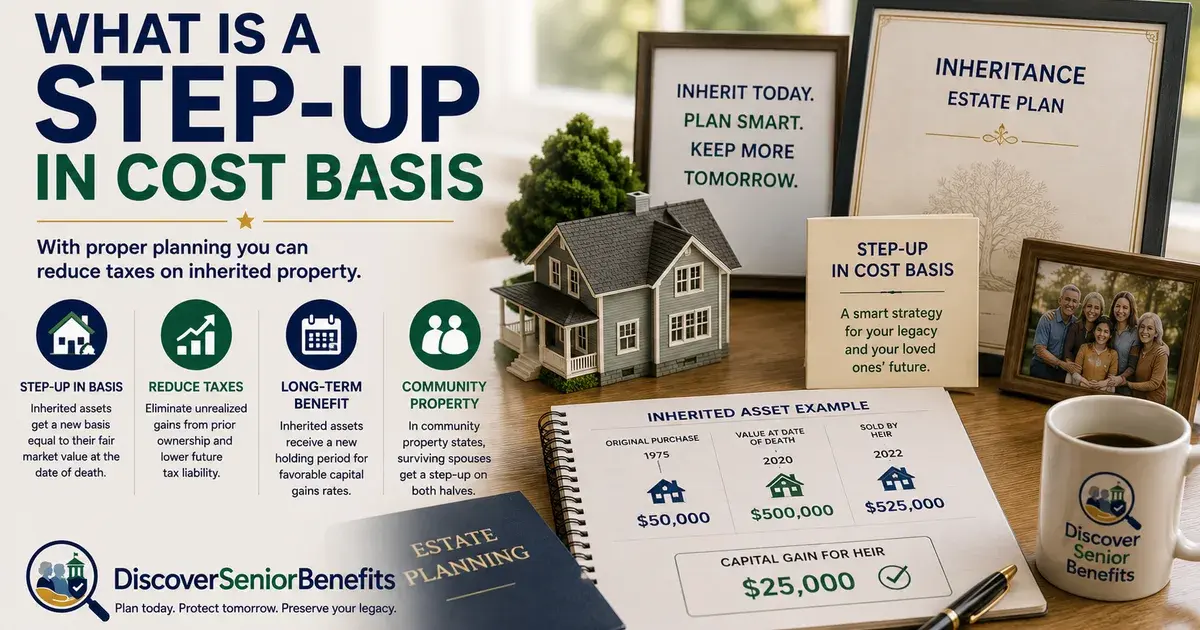
Consider a home purchased in 1975 for $50,000. By the time the owner passed away in 2020, the home had grown in value to $500,000. The heir inherits the home with a new cost basis of $500,000 — not $50,000.
Two years later, the heir sells the home for $525,000. The taxable gain is only $25,000 — the appreciation that happened after the inheritance.
Without the step-up rule, the taxable gain would have been $475,000 (the difference between the original $50,000 purchase price and the $525,000 sale price). Using example tax rates of 15% federal and 5% state, that could mean roughly $95,000 in capital gains taxes owed — compared to a much smaller bill with the step-up. The savings can be substantial.
Which Assets Qualify — and Which Do Not
Assets that typically receive a step-up in basis:
- Real estate
- Individual stocks or bonds
- Mutual funds
- Art, furnishings, and collectibles
- Some business interests
Assets that do NOT receive a step-up in basis:
- Bank accounts and cash
- Certificates of deposit (CDs)
- 401(k)s and other employer-sponsored retirement plans
- IRAs
- Pensions
- Annuities
When you inherit a retirement account or annuity, you keep the original owner's cost basis. Withdrawals from these accounts are generally taxed as ordinary income.
Also note: assets passing from an irrevocable trust to an heir may not qualify for a step-up in basis. Confirm the details with a tax professional.
Long-Term Capital Gains Rates for Heirs
One additional benefit: when you inherit an asset, you automatically qualify for long-term capital gains tax rates — even if the original owner held the asset for only a short time. Long-term rates are generally lower than short-term rates.
For 2026, the federal long-term capital gains rates are:
- 0% — for single filers with taxable income up to $49,450; married filing jointly up to $98,900
- 15% — for income between those thresholds and $545,500 (single) or $613,700 (married filing jointly)
- 20% — for income above those amounts
Collectibles can be taxed at up to 28%. Higher-income taxpayers may also owe an additional 3.8% Net Investment Income Tax. Confirm current rates with a tax advisor, as thresholds can change.
Community Property States vs. Common Law States
Where you live matters a great deal for surviving spouses.
Community property states — including Arizona, California, Texas, and Washington — treat most assets acquired during marriage as equally owned by both spouses. When one spouse dies, the surviving spouse receives a full step-up in basis on both halves of jointly owned assets. This can eliminate all taxable gain up to the date of death.
Common law (separate property) states — such as New Jersey — only allow a step-up on the deceased spouse's share of jointly owned property. For example, if a couple jointly owns a home worth $600,000 (originally purchased for $500,000), the surviving spouse's new basis would be $550,000 — not the full $600,000. A $50,000 taxable gain remains.
Some states — including Florida, Kentucky, and Tennessee — allow community property trusts, which let married couples opt in to community property treatment even if they live in a common law state. A legal professional can explain whether this option makes sense for your situation.
Using Step-Up in Basis in Your Estate Plan
Understanding this rule opens up several planning strategies:
Gift mindfully. Giving appreciated assets (like stock or real estate) while you are still living passes your original cost basis to the recipient. They could face a large tax bill when they sell. Leaving those same assets in your estate instead allows heirs to receive a step-up in basis. For 2026, you can gift up to $19,000 per person per year without triggering gift tax reporting.
Bequeath highly appreciated assets. The bigger the gain, the bigger the tax savings from a step-up. Consider leaving stocks or real estate that have grown significantly in value to heirs through your will, rather than selling them yourself.
Weigh estate taxes vs. capital gains taxes. If your estate is large enough to be subject to federal estate tax (the exemption is $15 million per person in 2026), holding onto appreciated assets may not always be the best move. A tax advisor can help you compare the two tax burdens. State estate taxes may also apply at lower thresholds.
Consider charitable giving. Donating highly appreciated assets to a qualified charity can avoid capital gains taxes entirely. Within certain limits, the donor may also receive an income tax deduction, and the asset is removed from the estate.
Every person's tax situation is different. Confirm your options with a qualified tax advisor and financial professional before making decisions.
See which of these programs you may qualify for. Free, no SSN, about five minutes.
Discover my benefitsNot legal or financial advice. The agency makes the final eligibility decision.
Related articles
4 min read
Long-Term Care: Options and How to Pay for It
Nearly 7 in 10 people turning 65 will need long-term care at some point. Understanding your payment options — from insurance to Medicaid — can protect your savings and ease the burden on your family.
4 min read
How Seniors Can Get Help Paying Heating Bills This Winter
Federal LIHEAP funding flows to every state as a heating-bill assistance program — and seniors often get priority access. Here is what to know about eligibility, how to apply, and the long-term fix that cuts energy bills for good.
4 min read
Medicare Open Enrollment 2026: Key Dates & Cost-Saving Programs
Medicare Open Enrollment runs October 15 to December 7, 2026. Here is what to do before the deadline — and two programs that can cut costs year-round.
Ask this article
Get answers about this article from the assistant on any paid plan.