· 5 min read
2027 Social Security Letter: Which Line Matters for Your Birth Year
A 3.6% raise is coming in 2027, but the line on your Social Security letter that matters depends on the year you were born. Here is what each age group should check before January.
Key takeaways
- Social Security announced a 3.6% raise for 2027, but the amount that reaches your bank account is lower after Medicare takes its share.
- People who claimed early and still work can have whole checks held back for months, and that money returns later as a small permanent raise.
- A new tax deduction of up to $6,000 for people 65 and older runs only for tax years 2025 through 2028, so birth year decides how many years you get it.
- The higher earner's claiming age sets the survivor's check for life, so it is a household decision.
- Check your tax withholding, your required withdrawal dates, and any old marriage or government pension rights before the year ends.
Want to know which programs fit your situation? A free check shows what you may qualify for in about five minutes. No SSN.
Discover my benefitsWhat the 2027 letter says, and what it leaves out
Social Security announced a 3.6% raise for 2027. It is the biggest increase since 2023. The average retired worker would go up about $75 a month.
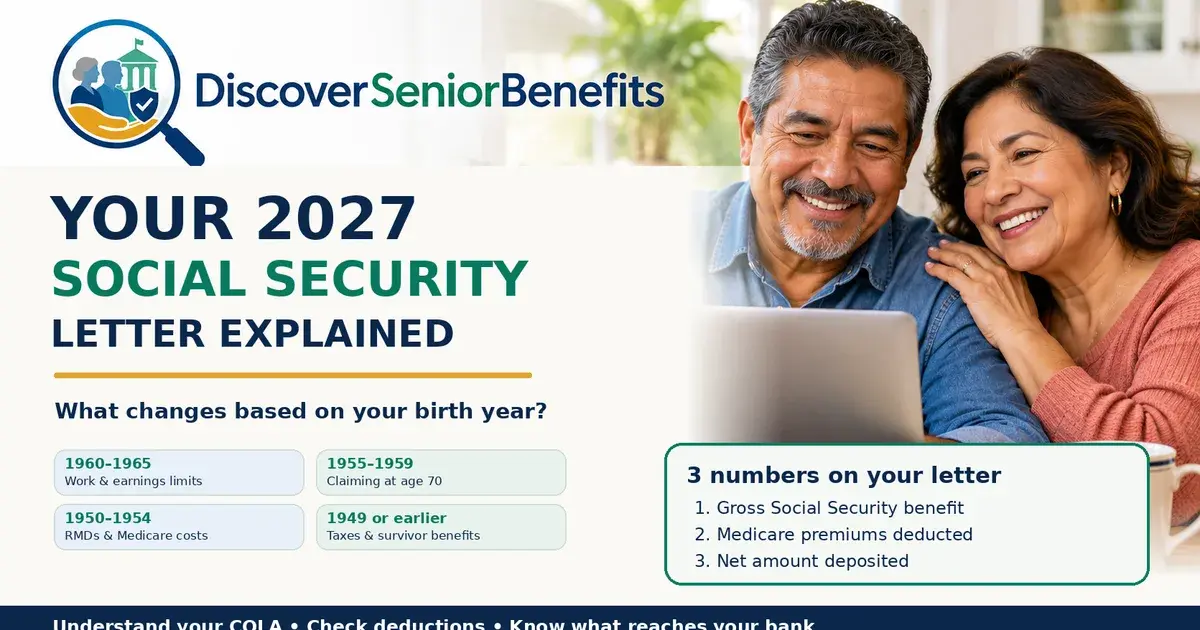
Your letter has three numbers, not one:
- Your new benefit before anything comes out.
- What comes out for Medicare.
- What actually reaches your bank account.
The Medicare Part B premium is $22.90 a month this year. Medicare trustees projected about $29.50 for 2027. The official number usually comes out in November. If it lands near that projection, most people keep most of the raise.
The letter appears first in your online My Social Security account in late November. The paper copy comes in December.
One more envelope matters. If Social Security decides it paid too much, it sends an overpayment notice. Since April 2025, the default is to keep half of your monthly check until the debt is repaid. You can ask for a smaller monthly amount, or ask to have the debt waived if it was not your fault. Answer these notices quickly.
Born 1960 to 1965: the earnings limit and the new tax deduction
Take Carol, born in 1961. She claimed at 62, is now 65, and earns $43,560 a year. Until full retirement age, earnings above a yearly limit are checked. For 2027 the limit is $25,560. Social Security holds back $1 of benefits for every $2 over the limit.
Carol is $18,000 over, so $9,000 is held back. Social Security takes whole checks, not pieces. At $1,800 a check, that is five checks. January through May bring nothing. Full checks start in June.
The money is not lost. At full retirement age, Social Security recalculates the benefit as if she had claimed those months later. The result is a slightly larger check for life. Whether that is a good trade depends on how long she lives and whether savings can cover five months of bills.
In the year you reach full retirement age, the limit jumps to $67,920. The penalty drops to $1 for every $3 over, and only months before your birthday count. After your birthday month, there is no limit. People born in 1960 reach a full retirement age of exactly 67 in 2027. Disability checks turn into retirement checks at that point on their own.
A new deduction for people 65 and older is worth up to $6,000 per person, on top of the regular standard deduction. It exists only for tax years 2025 through 2028, and you must be 65 by December 31 of the year. By birth year:
- Born 1960: four years.
- Born 1961: three years.
- Born 1962: two years.
- Born 1963: one year, 2028.
- Born 1964 or 1965: none under the law as written today.
The deduction shrinks by 6 cents per dollar once income passes $75,000 for a single person or $150,000 for a couple. It does not change how much of your Social Security is taxable. Required withdrawals from IRAs and old 401(k) plans start at 75 for this group. If you claimed within the last 12 months and have second thoughts, you can withdraw the application once by paying back what you received.
Married couples: the higher earner's claiming age is life insurance
When one spouse dies, the survivor keeps the larger of the two checks, not both. So the higher earner's claiming age sets the survivor's income.
Take Mike, born in 1962, with a full benefit of $3,000 at 67. Claiming at 62 pays 70%, or $2,100. Waiting to 70 pays 124%, or $3,720. If he claimed early, his wife's survivor check is capped at 82.5% of his full amount, or $2,475. If he waited until 70, her check is $3,720. That is $1,245 more every month for as long as she lives.
A survivor can start benefits as early as 60, at about 71.5% of the full amount, or wait for 100% at survivor full retirement age. Waiting past that adds nothing.
The tax side also changes. A survivor files as single. The senior deduction drops from $12,000 to $6,000. Tax brackets get about half as wide. The income lines for taxing Social Security fall from $32,000 to $25,000. Planners call this the widow's penalty.
Practical steps after a death: there is a one-time $255 death payment, and it must be requested within 2 years. If you were getting a spousal benefit, it usually switches to a survivor benefit on its own. If you only had your own check, you have to call.
Born 1955 to 1959: no earnings limit, and a deadline at 70
Everyone in this group reaches full retirement age by the end of October. The earnings limit no longer applies. You can work as much as you want and nothing is held back.
Waiting past full retirement age raises your benefit by 8% a year, but not past age 70. People born in 1957 turn 70 in 2027. Social Security does not start the check on its own. Take Dennis, who turns 70 in March 2027 and would get $3,712 a month. If he applies in December, back pay reaches only 6 months. He would lose three checks, about $11,136. You can apply up to 4 months before the month you want benefits to start.
If you claimed early and are past full retirement age, you can ask Social Security to suspend your check. Each suspended month earns the same 8% a year, up to age 70. Linda, born in 1958, gets $1,500. Suspending for 12 months gives up $18,000 to gain $120 a month for life. That takes about 12 years to earn back. Two cautions: anyone collecting on your record is paused too, and Medicare then bills you directly for Part B.
If you are widowed and not yet 70, a switch may be open. Social Security lets you take a survivor benefit first and switch to your own larger benefit later, or the reverse. You get the larger one, not both. Ask for a statement showing both amounts side by side.
Workers in this group should also update tax withholding. A payroll system does not know you qualify for the extra deduction, so a new W-4 can stop you from overpaying all year.
Born 1950 to 1954: required withdrawals and the two-year Medicare lens
People born in 1954 with an IRA turn 73 in 2027, the year the first required withdrawal is due. Take Ruth, with $480,000 in her IRA at the end of 2026. Dividing by the IRS divisor of 26.5 gives about $18,113, all taxable.
Ruth may delay the first withdrawal to April 1, 2028. But then a second one is also due by December 31, 2028. That stacks about $36,000 of taxable income in one year. If it pushes her from the 12% bracket into 22%, tax on $18,000 rises from about $2,160 to about $3,960. Stacked withdrawals can also shrink the senior deduction.
Medicare's income-related surcharge, called IRMAA, is based on your tax return from two years earlier. Big moves this year, like an IRA withdrawal or selling a house, show up on your Medicare bill in 2028. You can appeal only for certain life-changing events, such as the death of a spouse, divorce, stopping work, or a lost pension, using a form called SSA-44. A sale you chose to make does not count.
The income lines for taxing Social Security, $25,000 for a single person and $32,000 for a couple, were set in 1983 and 1993 and never raised. About 4 in 10 beneficiaries now pay tax on benefits. No more than 85% of your benefit is ever taxable.
If you were married 10 years or more to someone you are no longer married to, you may collect on their record. You must be 62 or older and not remarried. It does not reduce their check, and they are not told. If that former spouse died, a survivor benefit may exist. Social Security will not find you. You have to call.
Missing a required withdrawal carries a 25% penalty, or 10% if fixed within 2 years. You can combine IRA amounts and take the total from any IRA. Each 401(k) needs its own withdrawal.
Born 1949 or earlier: the email, the repeal, and the paperwork
In July 2025, Social Security sent a message saying the new tax law eliminates federal income tax on benefits for most people. That is not what the law did. It added the $6,000 deduction. For people with modest income, that may mean no tax owed. For others, tax is only reduced.
Take Frank, 80, with $28,800 a year in Social Security and a $30,000 IRA withdrawal. The new deduction saved him about $720. His tax was still about $2,055. If he stopped withholding because of the email, he would owe about $2,000 plus a possible underpayment penalty. If you stopped withholding after that email, run your numbers now.
If you are over 70 and a half, you can send money straight from an IRA to charity. This is called a qualified charitable distribution. Frank gave $3,000 this way and cut his tax by about $666 because less income reached his tax return. If Social Security is your only income, you very likely owe no federal tax. If tax was withheld from an IRA or pension, file anyway to get it back. Look for Schedule 1A on your return. If the deduction is missing, you can usually amend for up to 3 years.
The Social Security Fairness Act repealed the Windfall Elimination Provision and the Government Pension Offset. These rules cut benefits for people with government pensions from jobs that did not pay into Social Security. Benefits are payable back to January 2024. Many widows were told long ago that a pension wiped out a survivor benefit, so they never applied. Social Security cannot pay someone who never applied. A new application generally reaches back only about 6 months, so apply now.
Pick one trusted person to know where the December letter, Medicare notices, and the January SSA-1099 tax form arrive. If your income is modest, ask your state about Medicare Savings Programs, which can pay your Part B premium. Many eligible people have never applied. Confirm details with the agency, which makes the final eligibility decision.
Is Social Security running out, and the calendar to watch
Trustees reported in June that the retirement trust fund reserves are expected to run dry in the last quarter of 2032. After that, incoming taxes would cover about 78% of scheduled benefits unless Congress acts. That is about $1,693 on today's average check of $2,170. Congress has never let a scheduled cut happen, but a plan should include a margin.
Key dates:
- Now to December 7: Medicare open enrollment.
- November: Medicare announces the official Part B premium and the 2027 surcharge lines.
- Late November: the letter appears in My Social Security.
- December: the paper letter arrives.
- December 31: people on SSI get January's payment early.
- January: the raise appears in your first check.
This article is general information, not legal or financial advice. Confirm your own numbers with Social Security, the IRS, or Medicare.
Programs in this article
- How to apply for Supplemental Security Income (SSI) →
- How to apply for State Health Insurance Assistance Program (SHIP) →
- How to apply for Qualified Medicare Beneficiary (QMB) →
- How to apply for Specified Low-Income Medicare Beneficiary (SLMB) →
- How to apply for Qualifying Individual (QI) →
- How to apply for Senior Medicare Patrol (SMP) →
See which of these programs you may qualify for. Free, no SSN, about five minutes.
Discover my benefitsBenefits in your area
Pick your state to see the programs that serve your county.
Sources
Program facts in this article trace to these official pages, the same ones the eligibility rules cite.
- Supplemental Security Income (SSI) · ssa.gov · Last verified · November 17, 2026
- State Health Insurance Assistance Program (SHIP) · acl.gov · Last verified · November 17, 2026
- Qualified Medicare Beneficiary (QMB) · medicare.gov · Last verified · November 17, 2026
- Specified Low-Income Medicare Beneficiary (SLMB) · medicare.gov · Last verified · November 17, 2026
- Qualifying Individual (QI) · medicare.gov · Last verified · November 17, 2026
- Senior Medicare Patrol (SMP) · acl.gov · Last verified · November 17, 2026
Not legal or financial advice. The agency makes the final eligibility decision.
Related articles
5 min read
Social Security & Medicare Penalties: How to Avoid Them
Millions of Americans pay more than they should because of Social Security and Medicare penalties they never saw coming. Here is what each penalty is, why it happens, and how to protect yourself.
5 min read
4 Retirement Health Care Decisions to Get Right
Missing a health coverage enrollment window in retirement can mean higher costs that last for years. Here are the four decisions that matter most — and how to approach each one.
5 min read
Medicare Part D Changes, Social Security Tips, and What Seniors Need to Know Now
Major shifts in Medicare Part D drug coverage and Medicare Advantage plans are coming. Here is what seniors and caregivers need to understand — and do — before open enrollment.
Ask this article
Get answers about this article from the assistant on any paid plan.